Key Highlights:
- Growing markets gained 62% over the past 18 months, ahead of the 25% return from the Magnificent Seven
- US small-caps, value stocks and emerging markets have contributed to wider market leadership beyond mega-cap technology.
- Franklin Templeton expects firmer global liquidity to make the next phase of the rally more volatile
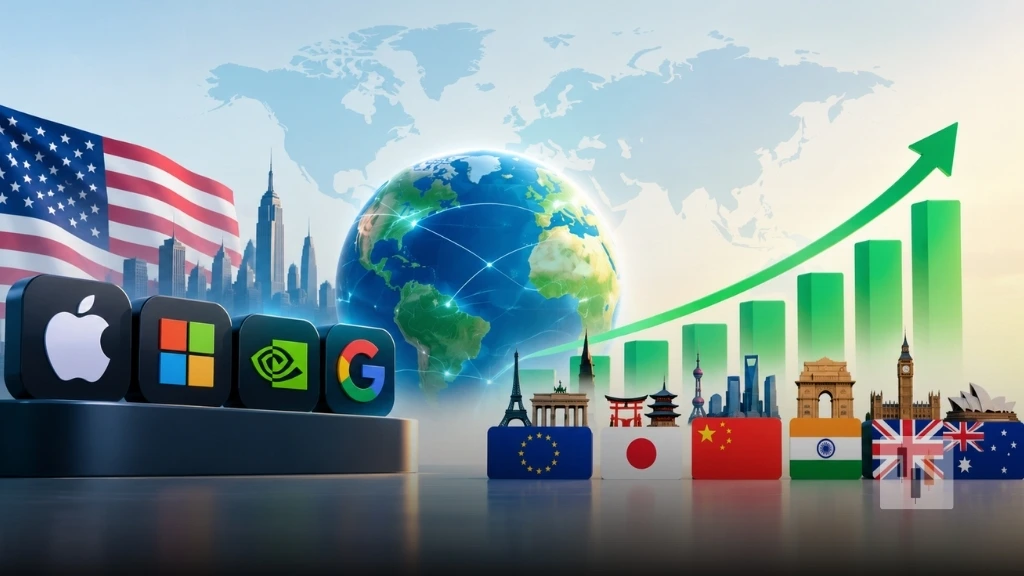
The global equity rally is becoming less reliant on US mega-cap technology stocks, with growing markets delivering a 62% return over the past 18 months. This is sharply ahead of the Magnificent Seven’s 25% gain. US small-caps and value stocks have also participated in the broadening rally, pointing to a wider distribution of market gains.
However, Franklin Templeton advised that stronger liquidity and more decisive leadership could make the next rally more sustainable. The shift comes as stakeholders balance gains with bond yields, financial policy expectations, and geopolitical risks.
How is Market Administration Moving Beyond US Technology Stocks?
The MSCI Emerging Markets Index has returned 62% over the past 18 months, while the Russell 1000 Value Index and Russell 2000 Value Index have gained 40% and 39%. By comparison, the Magnificent Seven stocks (Apple, Microsoft, Amazon, Alphabet, Meta Platforms, Nvidia and Tesla) have returned 25% over the same period.
The change marks a shift from the prior phase of the bull market, when a relatively small group of US technology companies accounted for a substantial share of market earnings. Franklin Templeton said its perception that market participation would broaden dates back to January 2025, when it argued that the concentration of returns in US mega-cap technology stocks was unlikely to continue. The fund house subsequently identified US small-caps, equal-weighted equities and emerging markets as niches where leadership could evolve.
Emerging markets have been a notable part of that shift. The MSCI EM Index has gained substantially more than the Magnificent Seven over the same 18-month timeline. This suggests stakeholders have increasingly looked beyond the costly US technology trade for opportunities across different geographies and market segments.
Franklin Templeton said improved mechanisms across a broader group of organizations, sectors, and geographical locations have helped support the shift in market administration. Wider participation does not mean the rally will continue at the same pace or in the same form. Instead, the fund house expects the market environment to become more reliant on individual company or regional fundamentals.
Why Could Firmer Liquidity Make the Next Phase More Selective?
After the smoother recovery from the March lows, Franklin Templeton said markets are moving into a more demanding phase, While gains continue to offer support for equities, global liquidity is becoming less adjustable. The fund house defines global liquidity based on the monetary police stance of major central banks. It assesses the number of central banks easing compared with those stringent policies.
From emerging markets, this changing backdrop could create a more mixed environment. The MSCI EM Index’s 62% return over the past 18 months shows that emerging market equities have already benefited significantly from the broader market rotation. However, firmer global liquidity could make foreign flows and valuations more sensitive to changes in interest rates and investor risk appetite.
Franklin Templeton continues to describe the broader bull market as intact, but its caution is focused on the character of the next phase rather than investors broadly buying across the market; leadership could become more selective as liquidity conditions change. The shift comes as global stakeholders assess gains alongside higher bond yields, changing expectations around financial policy and geopolitics.
This could mean that strong past performance does not necessarily translate into the same speed of gains ahead. Instead, individual markets and organizations may increasingly need to demonstrate improving fundamentals as investors become more selective.
The broader rotation away from US mega-cap technology therefore represents an important change in market administration, but the next phase could rely on liquidity, gains and risk appetite across geographical locations.